Conference futures sit between the Stanley Cup and division markets — and they’re often best priced
If I had to pick the single most underrated NHL futures market for UK punters, it’d be conference futures. Not Stanley Cup futures — those get all the attention and the pricing is correspondingly tight. Not division futures — those are too thinly traded for serious money. Conference futures sit in the middle, where the books haven’t compressed the margin as aggressively as they have on Stanley Cup, and the volume is high enough that you can get real positions on without moving the market. That sweet spot is where most of my futures EV comes from, and it’s hidden in plain sight on every UK book.
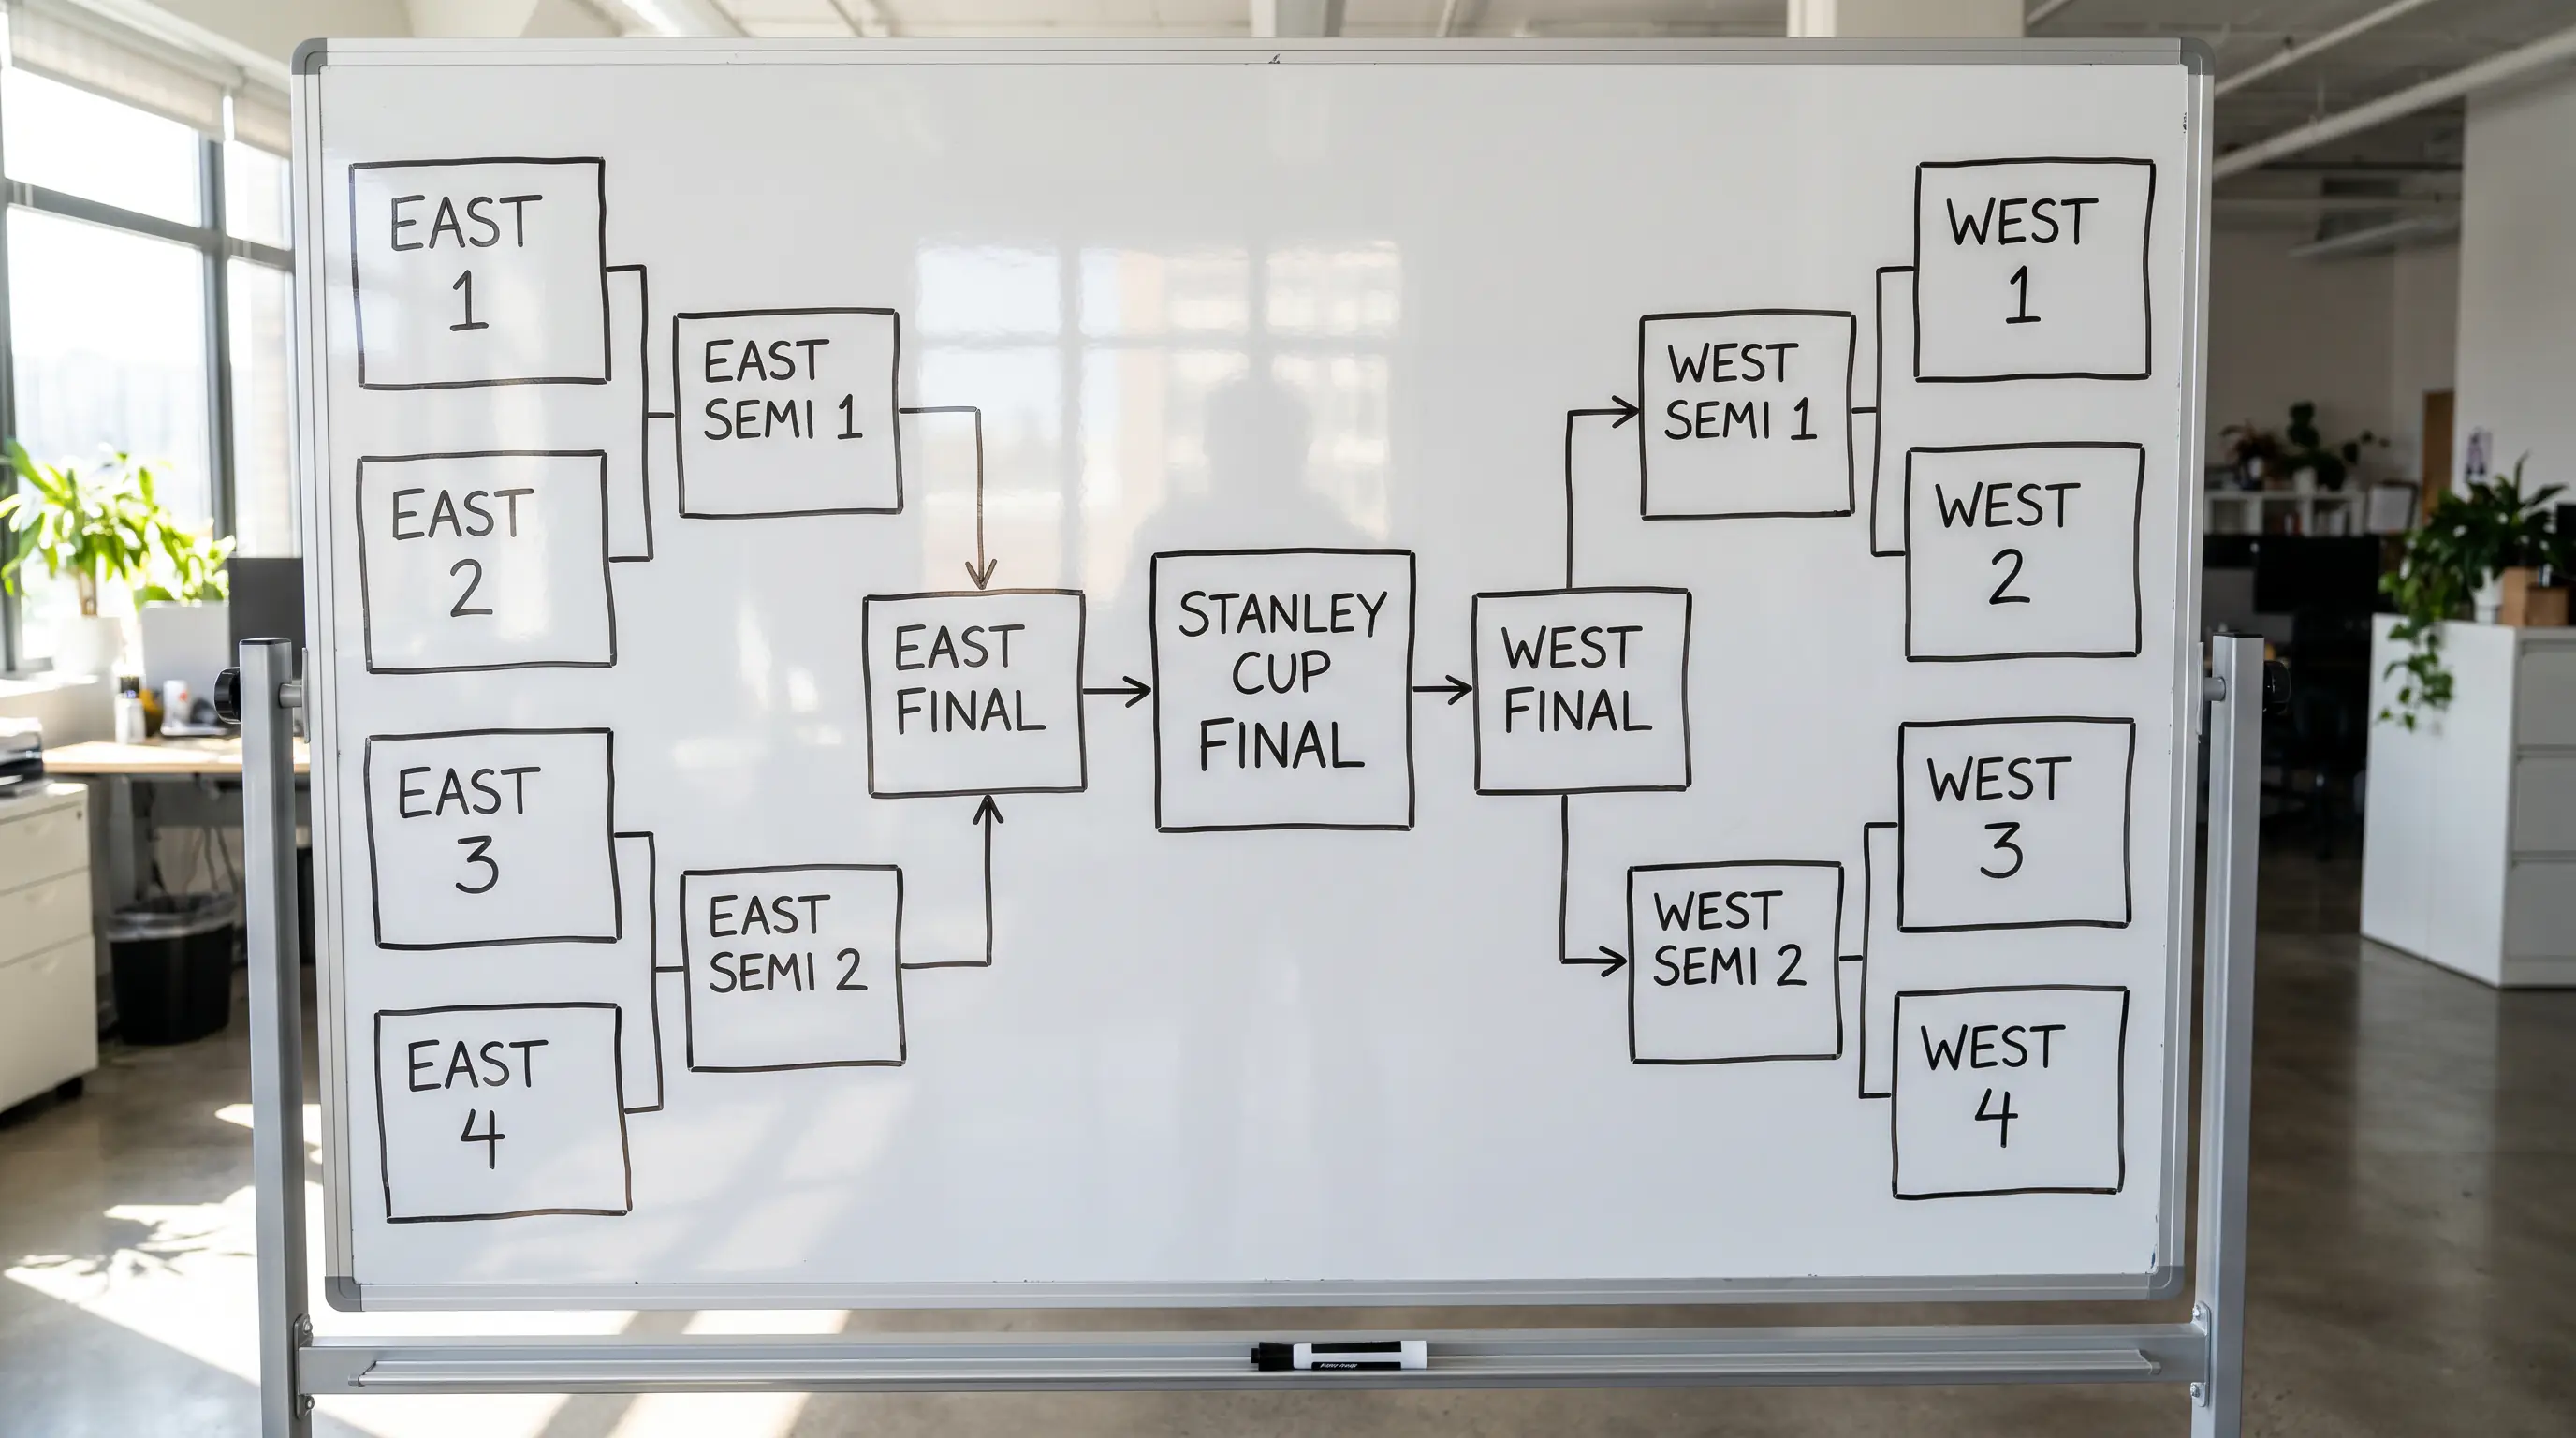
NHL conference futures price the outright winner of either the Eastern Conference Final or the Western Conference Final — effectively, which team wins the semifinal stage of the NHL playoffs and advances to the Stanley Cup Final. The market exists in parallel to the Stanley Cup futures market: any team backed in conference futures has to win its division round, its conference semifinal, and its conference final to settle the bet. The bet doesn’t extend to the Stanley Cup itself — winning the conference is the resolution.
The structural appeal of conference futures: tighter margins than Stanley Cup, deeper coverage than division futures, and a betting product that lets you take a view on which conference is stronger as well as which team wins it. UK punters who treat conference futures as a junior version of Stanley Cup futures miss the actual edge — conference markets behave differently because they resolve one round earlier and the field is half the size.
Mechanics: what settles and when it pays
Conference futures settle when the conference final concludes. The Eastern Conference Champion is the team that wins the Eastern Conference Final series; the Western Conference Champion is the team that wins the Western Conference Final series. The series winner advances to the Stanley Cup Final; the loser is eliminated.
The market opens in pre-season, typically July or August. Pricing in the pre-season window reflects roster construction, projected goalie matchups across the conference, and the previous season’s playoff result. The opening odds are a mix of model output and public sentiment, with the public sentiment usually weighting the previous season’s deep-playoff teams more heavily than the model would.
The market closes when the conference final ends. Some UK books leave conference futures open through the Stanley Cup Final on the conference winner — effectively converting it to a Stanley Cup futures position with the conference half already settled — but that’s an operational detail rather than a separate market.
The total field size: 16 teams in each conference, of which 8 make the playoffs in each conference. The conference futures market typically prices all 16 teams in each conference, with the non-playoff-likely teams at very long prices (200.0+) and the contenders clustered at 5.0 to 25.0.
The settlement risk is operational. Most UK books settle promptly after the conference final concludes — usually within hours of the deciding game. The settlement is on the official NHL result, which is unambiguous, so there’s no settlement dispute risk in conference futures comparable to player-prop markets where credit can be contested.
Pricing vs Stanley Cup: the margin gap
The margin gap between Stanley Cup futures and conference futures is the most important structural feature of the market. Stanley Cup futures markets typically carry a book margin (overround) of 10 to 15 percent across the full field — sum the implied probabilities of all teams and you get 110 to 115 percent. Conference futures typically carry a margin of 8 to 12 percent, sometimes as low as 7 percent at the tightest books.
The reason: Stanley Cup futures attract more public action because the market is more famous, and the operator can run a wider margin against that volume. Conference futures attract more sharp action and less public action, which forces the operator to tighten the margin to remain competitive.
The implication for the punter: the same model edge produces more realised EV in the conference futures market than in the Stanley Cup market. A team you assess as 8 percent likely to win the conference, priced at 14.0 (implied 7.1 percent), is a positive-EV position. The same team priced for Stanley Cup at, say, 30.0 might be priced at the equivalent implied probability after accounting for the additional round needed, but the margin cost is higher and the realised EV lower.
The average NHL franchise is valued at $2.1 billion in 2025 (Sportico) or $2.2 billion (CNBC), with year-on-year growth of 15 to 17 percent. The financial scale of NHL franchises supports a betting market deep enough that conference futures liquidity exists across the entire season, not just at major market openings. The operator can run conference futures all year because the underlying product is large enough to support continuous trading.
Hedging Stanley Cup futures with conference futures
The structural use case for conference futures that most UK punters overlook: hedging a long-horizon Stanley Cup position with a shorter-horizon conference position.
The scenario: in October you back Toronto at +1200 for the Stanley Cup. By March, Toronto is the Eastern Conference favourite at +200 (decimal 3.00) for the Stanley Cup. Your bet has appreciated significantly — the position is worth roughly 3x to 4x your original stake at fair value. You want to lock in profit but believe in Toronto’s chances.
The hedge: back Toronto’s conference final opponent or back the Western Conference field. The conference futures market gives you a cleaner hedge than the Stanley Cup market because it resolves at the conference final, removing the Stanley Cup Final variance from your hedged position. The Edmonton Oilers generated approximately $15 million per game during their 2025 Stanley Cup Final run — record per-game ticket revenue in hockey history — and that scale of single-game financial event is exactly the variance that the conference futures hedge removes from your portfolio.
The execution: if your Toronto Stanley Cup position is worth £400 at fair value, hedging with a £80 bet on the Western Conference favourite at 2.5 locks in £200 of value if the Western team wins the conference (and Toronto loses its conference final). The remaining £20 of variance covers the scenario where Toronto wins both conferences — your original bet pays out fully, and the £80 hedge loses but the £200+ Stanley Cup payout dwarfs it.
Division markets: the cousin product
NHL division markets price the winner of each of the four divisions: Atlantic, Metropolitan, Central and Pacific. Division winners are determined by regular-season points (with tiebreakers), not playoff results — the division market settles when the regular season ends in mid-April.
The division market is structurally different from conference futures because it’s a regular-season prediction rather than a playoff prediction. The price reflects which team will accumulate the most points across the full schedule, independent of how they perform in the playoffs.
The market is thin. UK book coverage of division winner markets is patchy — some books offer it, others don’t, and the limits are low across all of them. Division futures aren’t a primary product for the UK retail bettor; they’re a sidecar to the main conference and Stanley Cup markets.
The use case: division futures resolve before conference futures, providing partial information about a team’s strength before the playoff bracket is set. A team that wins its division is structurally favoured to advance further in the playoffs than a team that didn’t, all else equal. But the pricing on division futures doesn’t reliably translate into conference futures pricing because the playoff seeding mechanism creates non-obvious matchup outcomes.
The pillar market that conference futures sit beside
Conference futures and Stanley Cup futures share the same playoff bracket but resolve at different points and carry different margin structures. The full breakdown of how Stanley Cup futures are priced, what shifts the market across the regular season and the playoffs, and where the structural EV in long-horizon NHL betting sits is in our Stanley Cup futures analysis.
Articles
Prepared by the hockeybetonline.com editorial staff.
